U.S. Corporate Tax for Crypto Companies: How Crypto Is Taxed Under U.S. federal tax rules, digital assets are treated as property. A corporation’s sale, exchange, or other disposition can create a taxable gain or loss, calculated using the asset’s fair market value in U.S. dollars at the time of the transaction.
A company may owe tax even when no dollars change hands. Crypto received for goods or services can count as business revenue, while selling or spending it may create a separate tax result.
This guide explains how U.S. tax rules apply to crypto income, sales, spending, and losses, and how these activities are reported by corporations.
Key Takeaways
- Separate company activity from owners’ personal crypto activity; the business structure affects how income, gains, and losses are reported.
- Keep transaction records that connect each asset’s basis, value, date, and business purpose. These details help explain the tax result when crypto is sold, exchanged, or spent.
- Account for crypto received as business income, then track what happens when the company later disposes of those assets.
- Understand how a transaction’s value at disposal compares with its basis to identify a gain or loss, and how the company’s tax classification affects its treatment.
- The Infrastructure Investment and Jobs Act of 2021 expanded broker information-reporting rules mainly under Internal Revenue Code §6045 for certain digital asset transactions, according to United States Congress.
Do crypto taxes impact businesses?
Yes. U.S. businesses may have tax and reporting obligations when they receive, sell, exchange, or otherwise dispose of digital assets. The applicable return depends partly on the business’s federal tax classification.
Broker reporting rules affect which transaction information may be reported to the Internal Revenue Service. Businesses still need records that explain their activity and tax calculations.
Digital Asset Return Questions and Forms
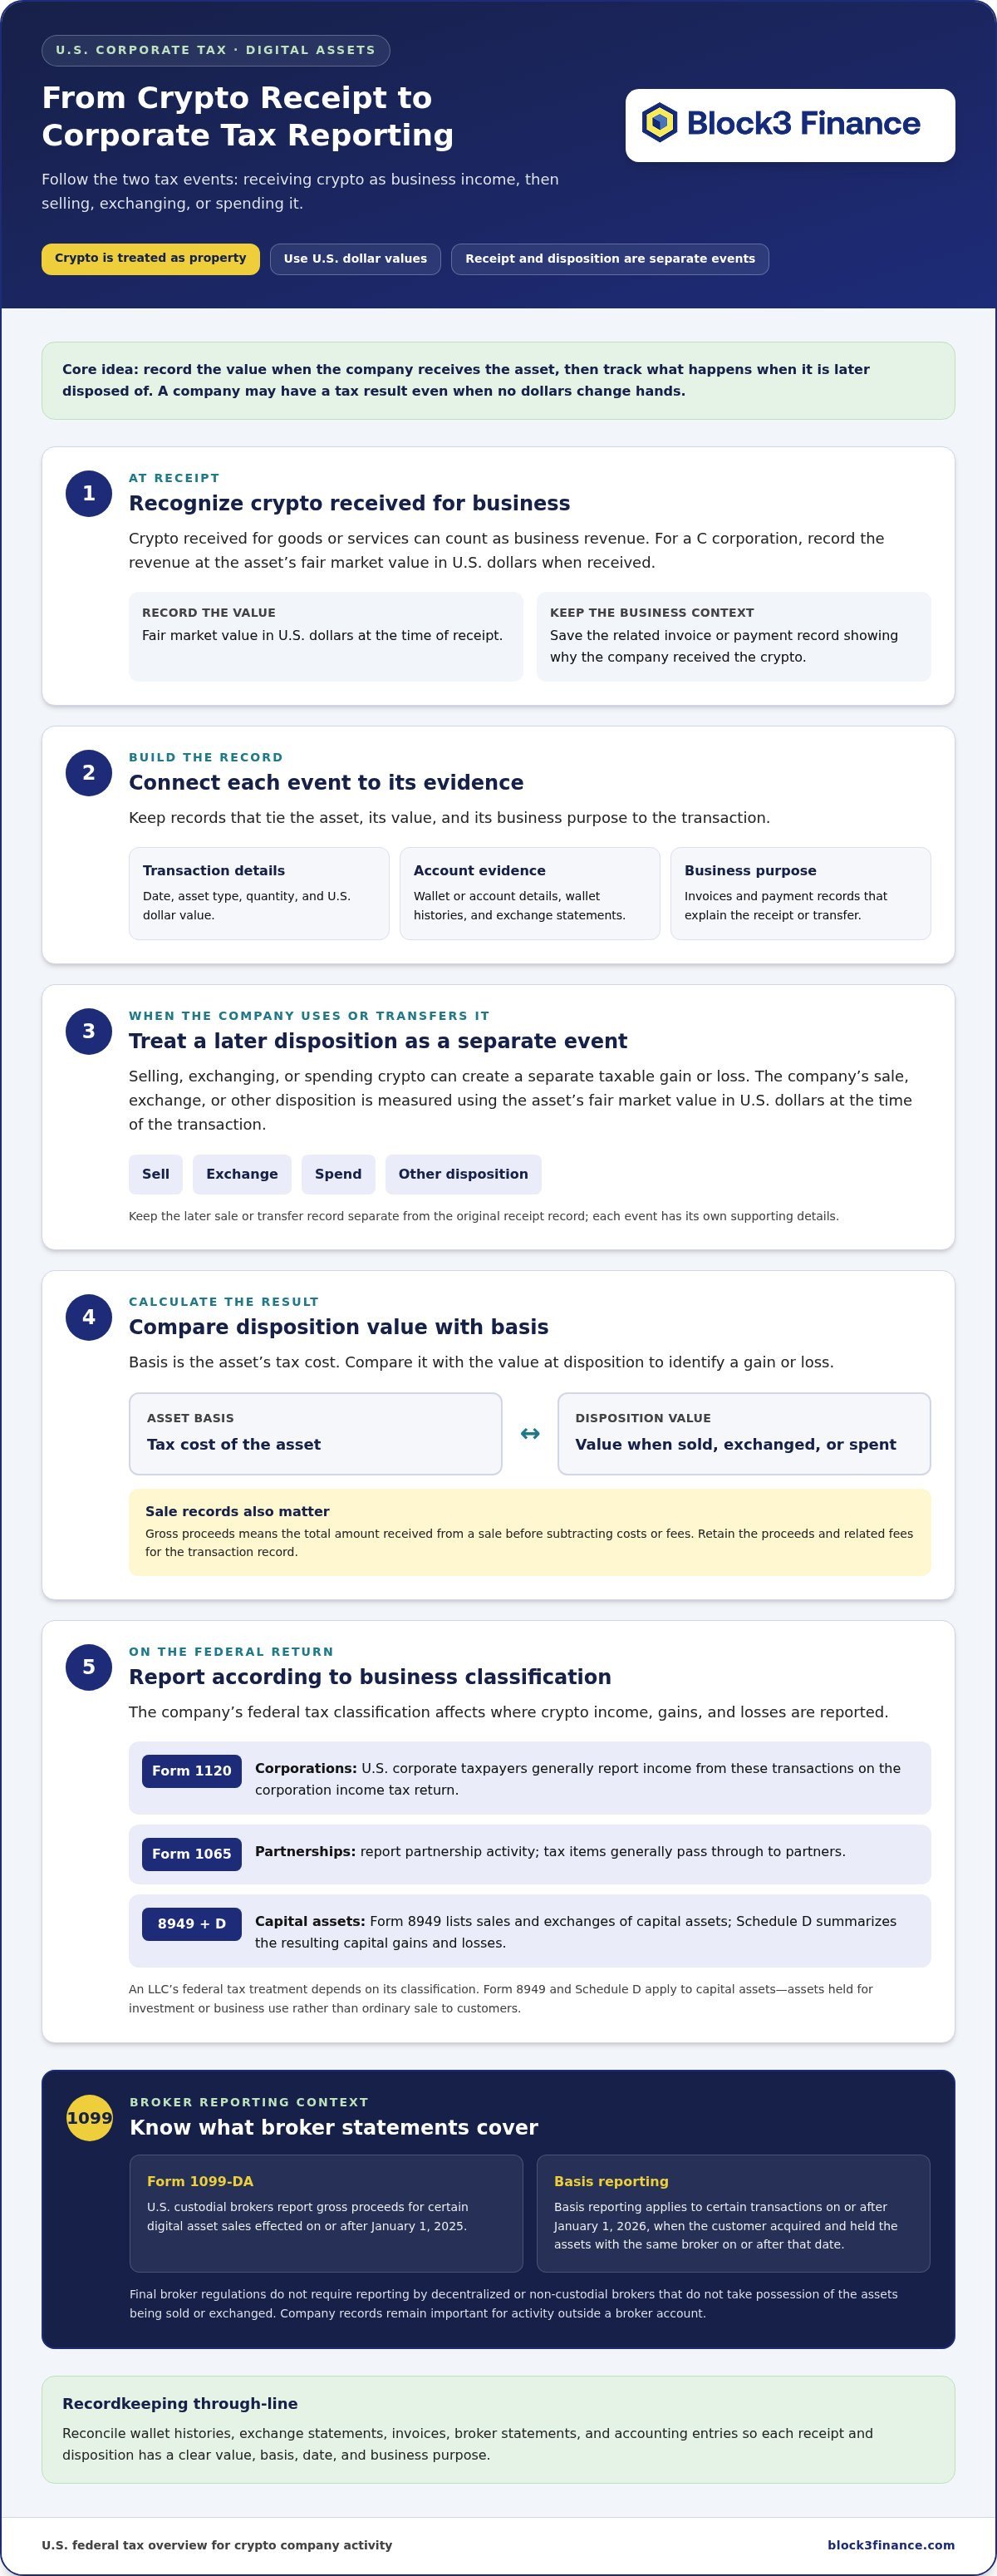
A digital asset return question asks whether a business received, sold, exchanged, or otherwise disposed of digital assets during the tax year. U.S. corporate taxpayers generally report income from these transactions on Form 1120, the U.S. Corporation Income Tax Return, according to the Internal Revenue Service. Partnerships report the digital asset question on Form 1065.
- Form 1120: the federal income tax return used by corporations.
- Form 1065: the federal return partnerships use to report partnership income.
- Form 8949 and Schedule D: Form 8949 lists sales and exchanges of capital assets, meaning assets held for investment or business use rather than ordinary sale to customers. Schedule D summarizes the resulting capital gains and losses.
These distinctions matter because both the company’s entity type and the asset’s role affect where transactions are reported. A pass-through entity generally passes income or loss to its owners’ tax returns instead of being taxed at the entity level.
Tax Treatment Across Business Structures
Business structure determines whether crypto income is reported by the entity or passed to owners. A C corporation generally files its own federal return. An LLC’s federal tax treatment depends on its classification, while a partnership reports activity on Form 1065 and generally passes tax items to its partners.
What are the tax differences between C corporations, LLCs, and partnerships for crypto businesses? C corporations report at the entity level; LLCs may be taxed as corporations, partnerships, or disregarded entities, depending on classification. Partnerships report on Form 1065, with partners generally reporting their allocated results.
The Infrastructure Investment and Jobs Act of 2021 expanded broker information-reporting rules mainly under Internal Revenue Code §6045 for certain digital asset transactions, according to United States Congress.
Noncompliance Penalties and Audit Risks
What are the U.S. tax rules for crypto exchanges, custodians, and other digital asset businesses? Custodial brokers report gross proceeds on Form 1099-DA for certain sales effected on or after January 1, 2025. Final broker regulations do not require reporting by decentralized or non-custodial brokers that do not take possession of assets being sold or exchanged.
What penalties and audit risks do crypto companies face for tax noncompliance? Inaccurate returns or missed reporting obligations can lead to penalties and examination risk. The IRS provided transitional guidance and penalty relief generally for calendar years 2025 and 2026 for certain broker reporting and backup withholding requirements. The OECD’s Crypto-Asset Reporting Framework supports automatic cross-border exchange of crypto-asset information.
Consistent records help reconcile company books with broker statements and return entries. A U.S. tax filing and reporting process can bring those records together for review.
How is crypto taxed?
For U.S. tax purposes, a company’s receipt of crypto and its later disposition are separate events. To manage corporate tax for crypto companies, record each event’s value, business purpose, and supporting documentation.
How are cryptocurrency transactions taxed for C corporations in the United States? A C corporation generally recognizes revenue when it receives crypto for goods or services, then calculates a gain or loss if it later sells, exchanges, or otherwise disposes of the asset.
Transaction Records and Reporting
Transaction records should connect each crypto event to its business purpose and tax treatment. For every receipt or disposition, retain the date, asset type, quantity, U.S. dollar value, wallet or account details, and related invoice or payment record.
- Save wallet histories and exchange statements to support transaction dates and quantities.
- Keep invoices and payment records that show why the company received or transferred crypto.
- Reconcile these records against broker statements and accounting entries.
For example, bitcoin received for services is recorded as revenue at its value when received. A later sale is a separate event, with its own proceeds and fees. What IRS reporting and information-return requirements apply to crypto businesses? Corporations report relevant income on their federal returns, while brokers have separate duties for certain transactions. The Infrastructure Investment and Jobs Act of 2021 expanded broker information-reporting rules mainly under Internal Revenue Code §6045 for certain digital asset transactions, according to United States Congress.
Gross proceeds means the total amount received from a sale before subtracting costs or fees. U.S. custodial brokers, which hold customers’ digital assets, must report gross proceeds on Form 1099-DA for certain digital asset sales effected on or after January 1, 2025. Basis means the asset’s tax cost, used to calculate gain or loss. Basis reporting applies to certain transactions occurring on or after January 1, 2026, when the customer acquired and held assets with the same broker on or after that date. Company records remain important for activity outside that broker account.
Corporate Income Reporting and Tax Rate
Corporate income reporting includes crypto-related revenue and disposition results on the company’s federal return. Correct classification matters because it determines how each event contributes to reported taxable income.
U.S. corporate taxpayers generally report income from digital asset transactions on Form 1120, the U.S. Corporation Income Tax Return, according to the Internal Revenue Service. A C corporation reports its own taxable income; crypto activity does not create a separate corporate tax rate. What is the U.S. federal corporate income tax rate for crypto companies? The applicable rate follows federal corporate tax rules, not a special rate based solely on crypto activity.
When a company receives crypto for goods or services, record its value as revenue at receipt. If it later exchanges or spends the asset, record that disposition separately. Reconciling transaction data with Form 1120 helps explain how events flow into the return, supporting a disciplined approach to corporate tax for crypto companies. Companies can discuss crypto tax reporting needs with a tax professional.
Are crypto losses tax deductible?
For U.S. businesses, a crypto loss may reduce taxable gains, but the result depends on the asset’s tax classification and the company’s structure. A price decline alone doesn’t establish a deductible loss. Identify the relevant transaction and calculate the result using the asset’s basis and value at disposition.
Basis is generally the company’s tax cost in an asset. For crypto received as payment, recording its value when received helps establish the starting basis for a later sale or exchange. At disposition, compare the amount realized with that basis: proceeds above basis produce a gain, while proceeds below basis produce a loss. Fees can affect proceeds, so record them with the transaction.
For example, selling crypto for $17,000 with $500 in fees leaves $16,500 in reportable proceeds. Against a $15,000 basis, that produces a $1,500 gain. The calculation turns on documented proceeds, fees, and basis, not simply the asset’s current market price.
Holding period also affects how a capital gain or loss is classified. U.S. crypto held for one year or less before disposition is generally treated as short-term; an asset held for more than one year may produce a long-term result. In the supplied example, exchanging crypto with a $10,000 basis for land worth $12,000 after a 10-month holding period creates a $2,000 short-term capital gain.
Corporate treatment differs from the familiar individual capital-loss deduction. Corporations can use losses from crypto transactions to offset gains and reduce overall tax liability, but the individual rule allowing a deduction against ordinary income up to $3,000 shouldn’t automatically be applied to a corporation. Entity classification matters: an LLC taxed as a partnership may pass tax items through to members, while a C corporation reports its own results.
A capital loss carryback applies a current-year loss against eligible gains from an earlier tax year. It isn’t available in every case involving a crypto business. The entity’s federal tax classification and the type of loss determine whether prior-year treatment is available; an LLC’s legal label alone doesn’t settle the question.
For each particular asset, preserve acquisition records, wallet transfers, exchange statements, transaction fees, and disposition details. Treasury Regulation Section 1.1012-1(h) through (j) addresses crypto basis-tracking methodologies. Consistent records help distinguish a taxable disposition from an internal transfer and support calculations reported on Form 8949 and Schedule D when applicable.
U.S. tax treatment of crypto sales and spending
Under U.S. federal tax rules, selling or spending digital assets can create a taxable disposition. The holding period, asset basis, and value at the time of the transaction shape the result.
Tax Treatment of Crypto Sales
A crypto sale is a disposition that may produce a capital gain or loss. The company compares its basis with the amount realized, rather than treating the full sale proceeds as the taxable result.
To calculate the gain or loss, subtract the asset’s basis from its value at disposition, accounting for transaction fees where applicable. A sale, exchange, or other disposition uses fair market value at the transaction time. For digital assets held as capital assets, Form 8949 and Schedule D are used to report the calculation.
For example, selling crypto for $17,000 with $500 in fees leaves $16,500 in proceeds. Against a $15,000 basis, the result is a $1,500 long-term capital gain. The holding period also matters: crypto held for more than a year before sale can produce long-term treatment, while shorter periods can produce short-term treatment.
State sales-tax treatment is separate from federal income-tax treatment. Some U.S. states treat cryptocurrency like cash for sales-tax purposes, while others do not tax digital currencies. Records should identify the state and the underlying sale: accepting crypto alone doesn’t determine the sales-tax treatment of the goods or services.
Crypto Spending and Payment Tax Treatment
Spending crypto is a disposition because the company transfers an asset to pay for something. Its value when spent may differ from its basis, creating a gain or loss even when the payment covers an ordinary business expense.
For instance, a payer who spends cryptocurrency bought for $20 on a service after holding it for four years has a $30 long-term capital gain in the stated example. The company should record the payment’s date, the asset and quantity transferred, its fair market value, and the service or property received. That connects the spending event to both the expense record and the asset calculation.
A crypto payment also has a recipient-side tax result. In the U.S. example, paying $50 worth of cryptocurrency to a non-business computer repairer results in $50 of ordinary income for the recipient. The payer’s disposition and the recipient’s income are distinct tax consequences.
Hack-related losses require careful classification. Some LLCs may be able to deduct tax losses resulting from hacks, while individuals aren’t allowed to write off these events. The company’s entity classification and transaction records matter. Preserve incident documentation alongside wallet and exchange records to support the reported treatment.
Business income received in cryptocurrency
Under U.S. federal tax rules, cryptocurrency received for business activity can create income before the company converts it to dollars. Its value at receipt establishes the income amount and helps set the asset’s basis for a later sale, exchange, or payment. This two-stage treatment affects revenue recognition, recordkeeping, and tax compliance.
When a corporation receives crypto for goods or services, it reports the asset’s fair market value at receipt as revenue. Fair market value is the asset’s value in U.S. dollars at that time. For example, if a customer pays an invoice in bitcoin, the company records the payment’s dollar value when received, not when it later sells the bitcoin.
The receipt and any later disposition are separate events. If the company later sells or spends the bitcoin, it compares the proceeds or payment value with the basis established at receipt. A change in value between those events can create a gain or loss. Retain the receipt date, quantity, exchange or wallet records, invoice, and valuation support to trace both tax results.
Crypto mining has a related but distinct income rule. In the United States, cryptocurrency received from mining is taxable as ordinary income in the year it is acquired, based on its value at that time. Ordinary income is recognized as earned, unlike a capital gain from a later asset sale. Record each reward when acquired, along with its value and subsequent use.
Whether mining qualifies as a business matters. Cryptocurrency mining carried on as a bona fide business may allow deductions for ordinary and necessary expenses, including equipment, software, and electricity. Connect expense records to the mining operation and retain invoices, payment evidence, and accounting entries. This helps distinguish operating costs from crypto income.
Do not automatically apply individual tax rules to a corporation. U.S. crypto mining business profits may be subject to self-employment tax after eligible deductions, but that rule concerns self-employment and does not by itself establish a corporation’s tax treatment. Entity classification and the facts of the activity shape the reporting analysis. A corporate return should reflect the company’s actual structure and income sources.
For practical compliance, reconcile mining rewards and customer payments against wallet histories, exchange records, invoices, and the general ledger. Separate revenue at receipt from any later gain or loss, and document the valuation method consistently. A crypto tax review for business income can help organize those reporting questions around the company’s transactions and records.
Block3 Finance: Tax Filing and Reporting
Block3 Finance helps crypto businesses bring transaction records, income, gains, and losses into a coherent U.S. tax reporting process. Its Tax Filing and Reporting service can support companies preparing federal returns, while Monthly Accounting helps maintain consistent records throughout the year.
Turn to a Crypto Tax Accountant when business activity includes payments in digital assets, mining income, multiple wallets, or frequent dispositions that need reconciliation. Audits and Compliance can also help businesses organize tax records and address reporting requirements with greater discipline.
To discuss your company’s crypto tax filing and reporting needs, contact Block3 Finance.
Build tax readiness into your next growth stage
As your U.S. crypto operations evolve, include tax readiness when evaluating workflows, payment arrangements, and reporting systems. A clear process helps decision-makers connect business activity to financial records ahead of the next filing cycle.
Block3 Finance supports crypto businesses with Tax Filing and Reporting, Audits and Compliance, and Monthly Accounting. These capabilities can help bring tax preparation, record review, and ongoing bookkeeping into a more coordinated approach. For companies refining their corporate tax for crypto companies processes, the next step is to identify where transaction data, accounting records, and reporting responsibilities need better alignment.
Contact Block3 Finance to discuss your crypto tax needs and take a considered step toward stronger financial oversight.
Frequently Asked Questions
How does the Infrastructure Investment and Jobs Act affect cryptocurrency taxes?
The Infrastructure Investment and Jobs Act of 2021 expanded broker information-reporting rules mainly under Internal Revenue Code §6045 for certain digital asset transactions, according to United States Congress. This affects information brokers may report, not the basic need for a business to determine its own tax results. For example, a company reconciling an exchange statement should compare its reported transactions with its own wallet and accounting records.
Trading stock or investment?
The distinction depends on how the business holds and uses its assets. Crypto held for sale as part of ordinary business activity may be treated differently from crypto held as an investment, so the company’s purpose, trading practices, and accounting records matter. Document a policy for each asset category and apply it consistently. A token’s label alone doesn’t establish its tax classification.
What about nonfungible tokens (NFTs)?
NFT activity can have different tax consequences depending on why a business receives or holds a token and what happens next. For example, an NFT received as payment for services raises a different reporting question from one purchased and later sold. Under U.S. federal tax rules, digital assets are treated as property, but the NFT’s use and transaction facts shape the calculation. Keep purchase, sale, and payment records.
How do crypto companies calculate taxable income from mining, staking, and rewards?
For U.S. mining activity, cryptocurrency received is ordinary income in the year acquired, measured by its value at that time. Record each reward’s receipt date, quantity, and dollar value, then track later sales separately. Staking and other rewards also require transaction-level records, including when and how the asset was received. Don’t treat a later price change as the original reward amount.
Can crypto companies deduct token losses, trading losses, and operating expenses?
Companies can use losses from crypto transactions to offset gains, but the treatment depends on the entity and how the assets are classified. A price drop alone is not a realized loss from a disposition. For a bona fide U.S. mining business, ordinary and necessary expenses such as equipment, software, and electricity may be deductible. Keep invoices and link expenses to the business activity.
How does the 2025 U.S. digital asset broker reporting rule affect crypto companies?
For certain digital asset sales effected on or after January 1, 2025, U.S. custodial brokers must report gross proceeds on Form 1099-DA. A company may use that statement when reconciling sales, but it should compare the broker’s figures with its own transaction records. Broker reporting does not necessarily capture activity across every wallet or platform, so maintain records for transactions beyond the broker’s account.
How are crypto companies taxed at the state and local level in the United States?
State and local tax treatment can differ from federal treatment and varies by jurisdiction. For sales-tax purposes, some U.S. states treat cryptocurrency like cash, while others do not tax digital currencies. When accepting crypto, keep records showing the state connected to the sale, the product or service provided, and the payment value. These details help distinguish sales-tax questions from federal income reporting.
What tax obligations apply when a U.S. crypto company operates internationally?
Cross-border activity can involve information exchange as well as tax reporting. Map where the company operates, holds accounts, and conducts transactions. The OECD’s Crypto-Asset Reporting Framework, or CARF, establishes a framework for automatic exchange of crypto-asset information between countries. CARF is an information-exchange framework, not a substitute for determining filing obligations in the jurisdictions connected to the company’s operations.
Article by
Mahad Mohamed
Mahad Mohamed is an accountant and the CEO of Block3 Finance, with over 26+ years of Canadian and international tax and accounting experience. A crypto accounting specialist since the early days of Bitcoin, he has consulted for over 38 crypto companies and collaborated with legal professionals on regulatory matters. His expertise spans corporate reorganization, cross-border tax structuring (Canada & US), tax disputes, and CRA audits.
Previously, Mahad worked for the Canada Revenue Agency (CRA), Big4 accounting firms, and served as a Rulings Officer for the Federal Tax Authority of the UAE before acquiring Tax Partners in 2014.
Block3 Finance and Tax Partners has 44 full-time accountants and over 9,800+ clients.
Disclaimer
This article provides general information only and is current as of its publication date. It has not been updated and may be out of date. It does not constitute legal advice and should not be relied upon as such. Every tax situation is unique and may differ from the examples discussed in this article. If you have specific questions, you should seek the advice of our accountants for your unique circumstances.
Frequently Asked Questions
How does the Infrastructure Investment and Jobs Act affect cryptocurrency taxes?
The Infrastructure Investment and Jobs Act of 2021 expanded broker information-reporting rules mainly under Internal Revenue Code §6045 for certain digital asset transactions, according to United States Congress. This affects information brokers may report, not the basic need for a business to determine its own tax results. For example, a company reconciling an exchange statement should compare its reported transactions with its own wallet and accounting records.
Trading stock or investment?
The distinction depends on how the business holds and uses its assets. Crypto held for sale as part of ordinary business activity may be treated differently from crypto held as an investment, so the company’s purpose, trading practices, and accounting records matter. Document a policy for each asset category and apply it consistently. A token’s label alone doesn’t establish its tax classification.
What about nonfungible tokens (NFTs)?
NFT activity can have different tax consequences depending on why a business receives or holds a token and what happens next. For example, an NFT received as payment for services raises a different reporting question from one purchased and later sold. Under U.S. federal tax rules, digital assets are treated as property, but the NFT’s use and transaction facts shape the calculation. Keep purchase, sale, and payment records.
How do crypto companies calculate taxable income from mining, staking, and rewards?
For U.S. mining activity, cryptocurrency received is ordinary income in the year acquired, measured by its value at that time. Record each reward’s receipt date, quantity, and dollar value, then track later sales separately. Staking and other rewards also require transaction-level records, including when and how the asset was received. Don’t treat a later price change as the original reward amount.
Can crypto companies deduct token losses, trading losses, and operating expenses?
Companies can use losses from crypto transactions to offset gains, but the treatment depends on the entity and how the assets are classified. A price drop alone is not a realized loss from a disposition. For a bona fide U.S. mining business, ordinary and necessary expenses such as equipment, software, and electricity may be deductible. Keep invoices and link expenses to the business activity.
How does the 2025 U.S. digital asset broker reporting rule affect crypto companies?
For certain digital asset sales effected on or after January 1, 2025, U.S. custodial brokers must report gross proceeds on Form 1099-DA. A company may use that statement when reconciling sales, but it should compare the broker’s figures with its own transaction records. Broker reporting does not necessarily capture activity across every wallet or platform, so maintain records for transactions beyond the broker’s account.
How are crypto companies taxed at the state and local level in the United States?
State and local tax treatment can differ from federal treatment and varies by jurisdiction. For sales-tax purposes, some U.S. states treat cryptocurrency like cash, while others do not tax digital currencies. When accepting crypto, keep records showing the state connected to the sale, the product or service provided, and the payment value. These details help distinguish sales-tax questions from federal income reporting.
What tax obligations apply when a U.S. crypto company operates internationally?
Cross-border activity can involve information exchange as well as tax reporting. Map where the company operates, holds accounts, and conducts transactions. The OECD’s Crypto-Asset Reporting Framework, or CARF, establishes a framework for automatic exchange of crypto-asset information between countries. CARF is an information-exchange framework, not a substitute for determining filing obligations in the jurisdictions connected to the company’s operations.