Under U.S. federal tax rules, living outside the country doesn’t automatically remove crypto reporting obligations. For crypto tax for nonresidents, the key question is whether income is U.S.-source (from a source in the United States) or effectively connected with a U.S. trade or business (connected to conducting business in the United States), not simply where an exchange is based.
It’s understandable to worry that an unreported transaction could lead to penalties, but crypto activities can receive different tax treatment. The type of income and its connection to the United States help determine the reporting position.
This guide explains how U.S. rules treat crypto transactions, what nonresidents should know about reporting risks and deadlines, and how to assess federal tax rates. It also covers U.S. tax considerations when comparing jurisdictions, helping you understand your reporting position more clearly.
Key Takeaways
- Learn how U.S. property rules shape the reporting of crypto sales, exchanges, and income.
- Understand why an unreported transaction can create filing risks, interest, or penalties.
- See why some taxable activity must be reported even when no information return is issued.
- Review how filing deadlines and late penalties can affect nonresident taxpayers.
- Understand how U.S. tax treatment of crypto gains can depend on the applicable rules and circumstances.
How does a crypto tax professional determine the correct amount of income to report for a nonresident?
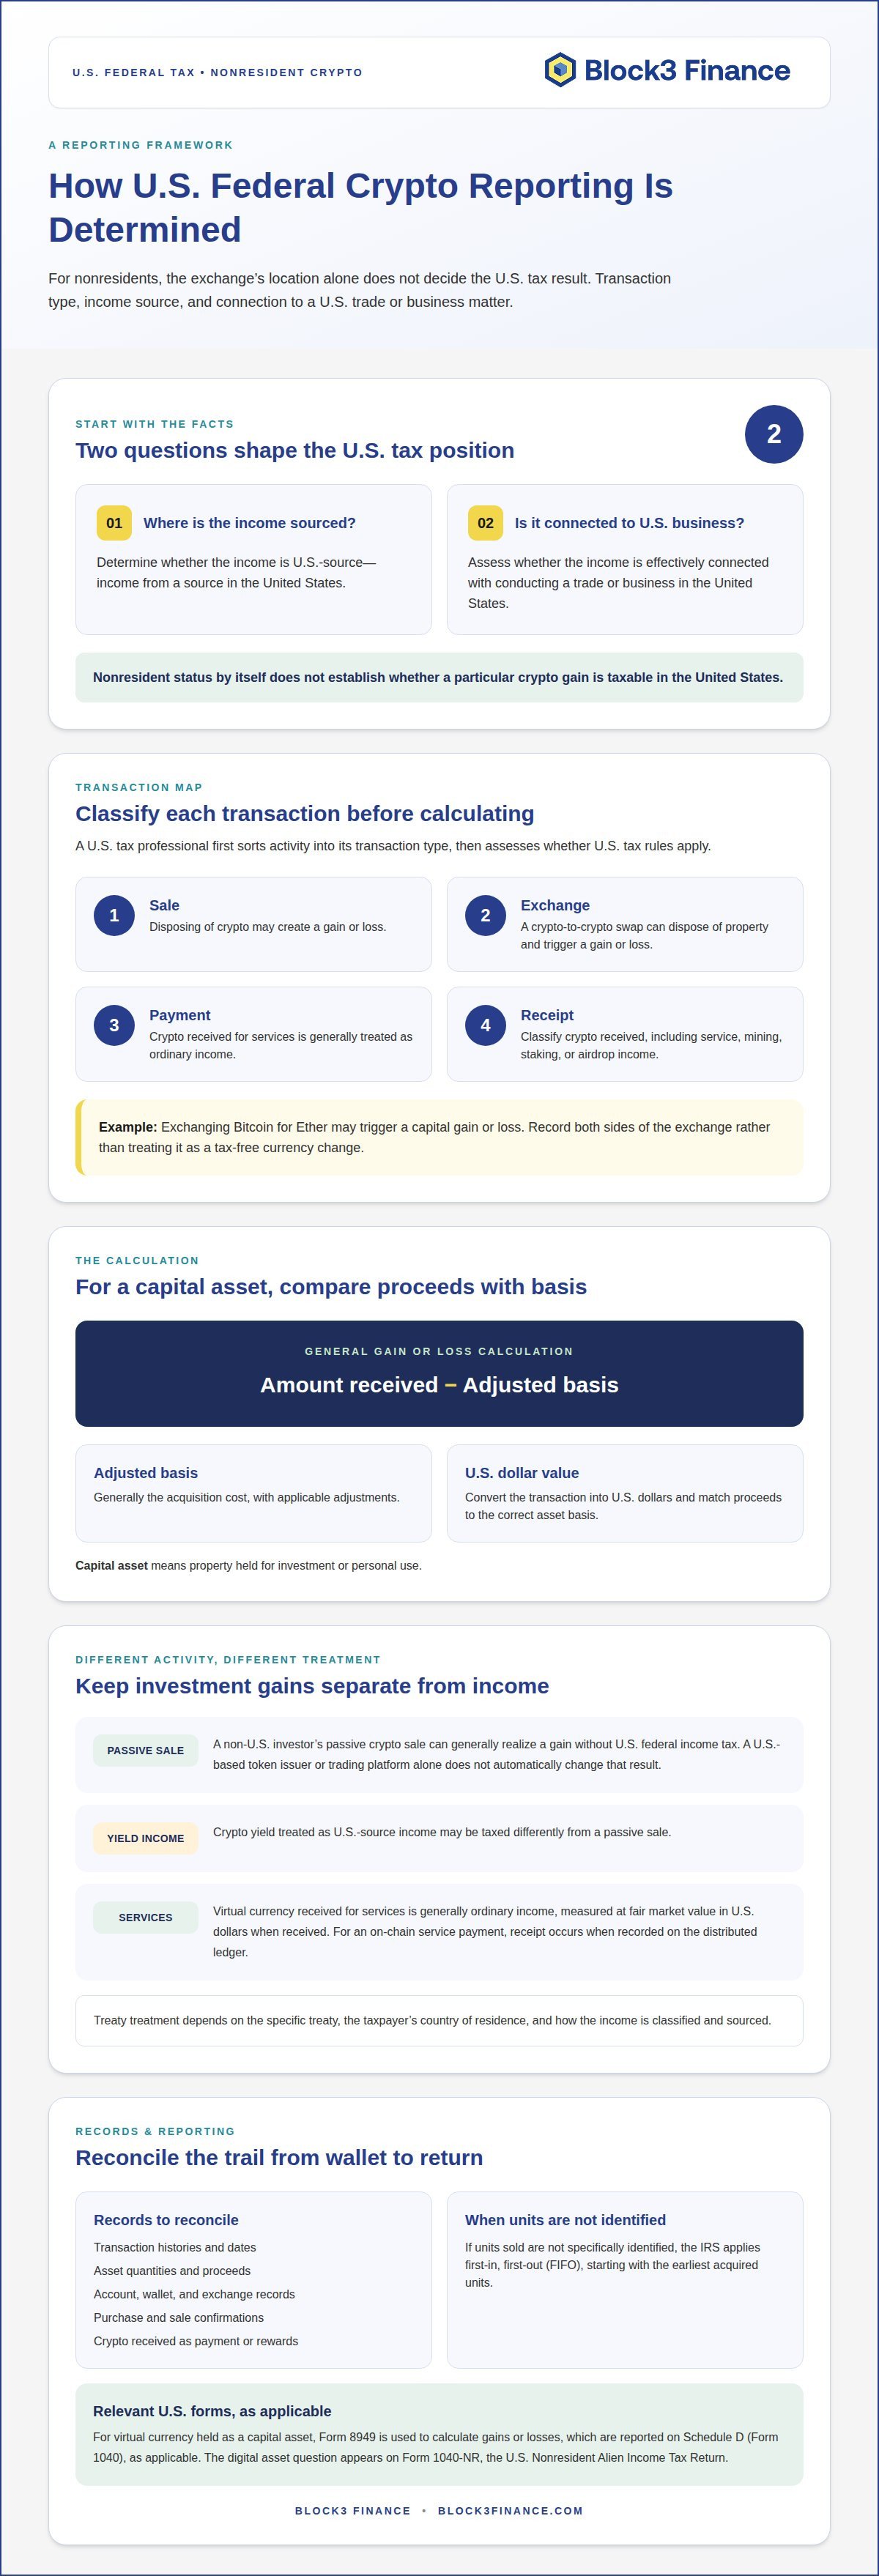
For U.S. federal tax purposes, cryptocurrency is treated as property, not ordinary currency. A tax professional first classifies each transaction as a sale, exchange, payment, or receipt, then determines whether U.S. tax rules apply to the income. Nonresident status alone doesn’t establish whether a particular gain is taxable in the United States. The income’s source and connection to a U.S. trade or business matter.
For a capital asset, a type of property held for investment or personal use, gain or loss generally equals the amount received minus the asset’s adjusted basis. Adjusted basis is generally the acquisition cost, with applicable adjustments. The transaction must be converted into U.S. dollars, and the proceeds matched to the correct asset basis.
U.S. tax rules generally distinguish passive investment sales from income connected with a U.S. trade or business. A non-U.S. investor’s passive crypto sale can generally realize a gain without U.S. federal income tax, even if the token issuer or trading platform is based in the United States. Crypto yield treated as U.S.-source income may be taxed differently from a passive sale. Classification is therefore central to calculating reportable income.
How do U.S. tax treaties affect nonresident crypto taxation? Treaty treatment depends on the specific treaty, the taxpayer’s country of residence, and how the income is classified and sourced. A tax professional considers those terms alongside domestic U.S. rules before determining whether a treaty changes the result.
Crypto received for services is treated differently from investment-sale proceeds. The Internal Revenue Service treats virtual currency received for services as ordinary income, income from work or business activities, rather than from selling an investment, generally measured at its fair market value in U.S. dollars when received. For an on-chain service payment, receipt occurs when the transaction is recorded on the distributed ledger. That value may also establish the asset’s basis for a later disposition.
A crypto-to-crypto swap can also dispose of property. Exchanging Bitcoin for Ether, for example, may trigger a capital gain or loss based on the value received and the Bitcoin’s adjusted basis. A professional records both sides of the exchange, rather than treating the swap as a tax-free change of currency. For virtual currency held as a capital asset, Form 8949 is used to calculate gains or losses, which are reported on Schedule D (Form 1040), as applicable.
To support the calculation, a professional reconciles transaction records, dates, asset quantities, proceeds, and basis across the available account and wallet history. If units sold aren’t specifically identified, the IRS applies first-in, first-out accounting, starting with the earliest acquired units. Accurate classification also separates investment gains from staking, mining, airdrop, or service income.
For U.S. filing support, crypto tax reporting can bring transaction calculations and the relevant return together. The result depends on the transaction type, its U.S. connection, and the taxpayer’s filing position, not simply on the exchange’s location.
What happens if I don’t report my Cryptocurrency income?
Under U.S. federal rules, failing to report taxable digital-asset income can result in accrued interest and penalties. The consequences depend on what was omitted, whether a return was required, and how the income connects to the United States. An exchange’s location alone doesn’t settle the reporting question. A U.S.-based platform or token issuer does not automatically make a passive crypto sale taxable to a non-U.S. investor.
The digital asset question appears on Form 1040-NR, the U.S. Nonresident Alien Income Tax Return, according to the Internal Revenue Service. A tax professional determines how the question applies to the taxpayer’s transactions and filing position. The answer must reflect activity such as crypto received for services, mining, staking, or an airdrop. It should not be based only on whether the taxpayer sold Bitcoin.
Review records that show what happened, when, and at what value. Relevant documents include transaction histories, wallet activity, exchange statements, purchase and sale confirmations, and records of crypto received as payment or rewards. Track transfers, swaps, and other dispositions, along with each asset’s fair market value in U.S. dollars. Matching these records helps distinguish taxable transactions from transfers between wallets owned by the same taxpayer.
Missing records can make it harder to establish acquisition dates, proceeds, and adjusted basis. For example, calculating a Bitcoin sale can be difficult if purchase history is missing or wallet transfers are mistaken for sales. Reconcile available records across accounts and wallets, then identify unexplained gaps before preparing the return. This supports consistent transaction treatment and reduces the risk of omitting reportable income.
Estate exposure is a separate issue from annual income reporting. U.S. estate tax on a non-U.S. individual’s U.S.-situs crypto assets, assets treated as located in the United States for tax purposes, may generally apply at a rate of 40% of their market value at death, according to the Internal Revenue Service. U.S. estate tax rules do not specifically determine the situs of crypto assets. A U.S. issuer or exchange, by itself, should not be treated as a definitive answer to where a crypto asset is situated.
Residence, income source, and the character of the transaction remain important when assessing U.S. tax exposure.
When transaction records span multiple wallets, platforms, or income types, a professional review of crypto tax reporting can help bring the documentation and filing position into alignment.
Taxable transactions without an information return
A U.S. tax return may need to report taxable crypto activity even when no exchange or payment platform provides an information return. An information return is a tax form supplied to the taxpayer and reported to the Internal Revenue Service. Its absence doesn’t determine whether a transaction is taxable or remove the obligation to report income, gain, or loss for the relevant tax year.
For U.S. federal tax purposes, selling virtual currency generally creates a capital gain or loss. A crypto-to-crypto exchange can also dispose of an asset, even when the taxpayer receives no cash. Payment for services in crypto may create ordinary income when received. Mining, staking, or receiving crypto after a hard fork can also affect the digital-asset tax treatment, depending on the activity.
A “No” answer may apply in a narrow example. For tax year 2021, a taxpayer whose only virtual currency transactions were purchases using real currency did not have to answer “Yes” to the Form 1040 digital asset question. That example concerns that tax year and those purchase-only facts. It doesn’t mean every person who bought crypto can answer “No” in another year.
Transfers between wallets or accounts belonging to the same taxpayer are non-taxable under the IRS virtual-currency FAQs. For example, moving Bitcoin from a personal exchange account to a wallet the same taxpayer owns isn’t a sale just because the asset changed locations. Keep records linking the sending and receiving addresses, quantities, dates, and transaction identifiers. Without them, a transfer can be mistaken for a disposal or unexplained receipt.
A crypto tax professional reviews records across the taxpayer’s exchanges and wallets, not only forms provided by a platform. Useful documentation includes:
- Exchange histories showing purchases, sales, swaps, fees, and dates.
- Wallet records that distinguish transfers between the taxpayer’s own accounts from payments to another person.
- Receipts showing digital assets received for services, rewards, mining, or other activity.
- U.S. dollar values and acquisition records needed to calculate gains or losses.
Reconciliation can identify transactions that may be reportable despite missing third-party paperwork. It also helps explain why a wallet transfer isn’t necessarily taxable while a sale or exchange may be. Taxpayers must report income, gain, or loss from taxable virtual-currency transactions for the relevant tax year, regardless of amount or whether they receive an information return. Complete records give a tax professional a clearer basis for preparing the return and classifying each event.
Cryptocurrency tax filing deadlines and penalties
For U.S. federal tax purposes, nonresidents should confirm the filing deadline that applies to their circumstances before planning their return. A nonresident with a U.S. filing obligation should treat that date as a key planning point, rather than waiting until crypto records are complete at the last moment. The return must account for relevant virtual-currency activities, including taxable sales, exchanges, and income received in digital assets.
The deadline and the amount due are separate matters. A return may report capital gains from selling crypto held as a capital asset, along with other taxable income. Capital gains are generally calculated by comparing proceeds with adjusted basis, the asset’s tax cost after applicable adjustments. A professional organizes transaction records by tax year so gains, losses, and income are reflected in the correct return.
Late filing can increase the amount owed. The stated U.S. late-filing penalty is generally 5% of unpaid taxes for each month or part of a month that a return is late. For example, if a return remains late into another month, the “part of a month” wording matters. The penalty is based on unpaid tax, not simply on the number of crypto transactions.
For 2025, the minimum penalty for filing more than 60 days after the due date or extended due date is $525 or 100% of unpaid tax, whichever is less. This rule illustrates why a missed filing date can matter even when a taxpayer has limited activity. The relevant comparison is between the stated minimum and the unpaid tax amount.
A crypto tax professional can connect the filing timetable with the transaction work. A review can identify whether activity produced capital gains, ordinary income, or reportable losses, then organize those items for the appropriate federal return. This distinction matters because taxable activity may occur even without an information return from an exchange. Missing third-party forms don’t determine whether reporting is required.
Before filing, resolve record discrepancies that could affect the return. For example, reconcile wallet transfers against exchange histories, separate a taxpayer’s own transfers from disposals, and identify transaction dates and values. These steps help establish the figures reported for the tax year and reduce avoidable omissions in the filing package.
A timely filing plan should account for the information required on the return, not just the submission date. When digital-asset records include trading, service income, or mining activity, classifying them may require additional coordination. Organizing records early gives the preparer a clearer basis for calculating the amount due and identifying filing issues before the applicable deadline.
U.S. tax treatment for crypto investors
For U.S. taxpayers, federal long-term capital-gains brackets for 2026 illustrate why one rate cannot describe every investor. The thresholds below are based on taxable income and filing status, so they are not a universal rate table for every taxpayer.
For 2026, the listed U.S. federal long-term capital-gains rates include:
- A single filer has a 15% rate on taxable income from $49,451 to $545,500, and a 20% rate on taxable income over $545,501.
- Married taxpayers filing jointly have a 0% rate on taxable income up to $98,900, a 15% rate from $98,901 to $613,700, and a 20% rate over $613,700.
These figures relate to long-term capital gains and specified filing categories. They should not be applied automatically to every U.S. tax return. The taxpayer’s filing status and the transaction’s U.S. tax treatment both matter. First establish whether the gain belongs in the relevant federal tax calculation; a bracket alone does not determine whether the United States taxes a particular crypto disposal.
The rate table also shows why a single headline percentage can mislead. A single filer and a married couple filing jointly face different taxable-income thresholds. The listed 15% rate begins at $49,451 for a single filer, while the joint-filer 0% band extends to $98,900. Those differences make filing category relevant to a rate comparison, but they do not replace the separate analysis of income classification and tax treatment.
For a practical U.S. tax review, keep three questions distinct: does the activity create a U.S. tax obligation, how is the income classified, and which federal rate framework applies? A long-term capital-gains bracket is not interchangeable with rates for ordinary income or yield. Nor does the phrase “low tax” settle whether a taxpayer must file or report a particular transaction under U.S. rules.
When reviewing a proposed investment plan, assess its U.S. tax consequences on their own terms. A focused review can connect filing status, transaction character, and the relevant U.S. federal calculation. Discuss your U.S. crypto tax position before making decisions based on a rate comparison.
Block3 Finance
Block3 Finance helps nonresidents bring crypto activity into a coherent U.S. tax reporting and accounting position. Its Tax Filing and Reporting, Audits and Compliance, Monthly Accounting, and Crypto Tax Accountant services can support transaction classification, records reconciliation, and U.S. return preparation. This support is especially useful when a filing position depends on distinguishing investment gains from business or service income, or when records need to align across reporting periods.
For a clear view of your U.S. crypto reporting needs, contact Block3 Finance.
Make your next crypto decision with clarity
Cross-border crypto activity is easier to manage when tax considerations are part of the decision, not an afterthought. A sound approach to crypto tax for non-residents connects your transaction history, filing position, and future plans in a clear financial picture. This can help you assess a proposed move, structure activity thoughtfully, and keep reporting decisions aligned as your crypto activity changes.
The next step is to bring your situation into focus. Consider where your transactions took place, how you received income, and which records support your reporting position. A professional review can help turn those details into a coherent plan for U.S. tax filing and ongoing compliance, without treating every investor or transaction alike.
Block3 Finance can help you move from uncertainty to a considered next step. Contact Block3 Finance to discuss your crypto tax needs and approach your next decision with greater confidence.
Frequently Asked Questions
Does the source of income matter?
Yes. For U.S. federal tax purposes, a non-U.S. individual is generally subject to tax on passive U.S.-source income or income effectively connected with a U.S. trade or business. The source and character of the income matter more than an exchange’s location alone. For example, a platform based in the United States does not automatically make a nonresident’s passive crypto sale subject to U.S. federal income tax.
How much tax will I pay?
There isn’t one rate for every nonresident crypto transaction. Crypto yield treated as withholdable U.S.-source income may face 30% gross withholding, according to the Internal Revenue Service. Yield treated as effectively connected income may be taxed at rates up to 37% for investing individuals and most trusts. For entities classified as corporations for U.S. tax purposes, the effective rate may be in the range of 45%. Treatment depends on income classification.
How can a crypto tax professional help nonresidents report their cryptocurrency gains to the IRS?
A crypto tax professional can organize transaction data into a filing position by reconciling exchange statements, wallet records, and asset basis. For example, if an exchange history omits a transfer into the account, matching wallet records can help distinguish a transfer from a purchase or taxable disposal. The professional can also separate investment gains from service or yield income, then prepare the relevant calculations and supporting return information.
Is Cryptocurrency reportable in Form 8938 (FATCA)?
For U.S. FATCA reporting, the IRS has not issued set regulations specifically addressing cryptocurrency reporting on Form 8938. This does not establish that every crypto holding is exempt from all reporting. Form 8938 concerns specified foreign financial assets, and the taxpayer’s status and asset details affect the analysis. A professional can assess those facts against the applicable U.S. filing position rather than treating every wallet as identical.
What if you Only Purchase Cryptocurrency and No Other Transactions Made during the year?
For U.S. tax year 2021, a taxpayer whose only virtual currency transactions were purchases using real currency did not have to answer “Yes” to the Form 1040 digital asset question. The example is limited to that tax year and purchase-only activity. A later sale, exchange, payment, reward, or other crypto receipt changes the transaction record and may affect the response and reporting analysis for that year.
How does U.S. crypto tax apply to nonresident aliens?
For crypto tax for non-residents, U.S. treatment generally turns on whether income is passive U.S.-source income or effectively connected with a U.S. trade or business. The label “nonresident alien” alone does not determine the tax treatment of every crypto event. A tax professional considers whether the activity is a passive investment disposal, yield, or business-connected income, then evaluates the relevant U.S. filing obligations for that category.
Are nonresident aliens taxed on cryptocurrency gains from U.S. exchanges?
Not solely because they used a U.S. exchange. A non-U.S. investor who passively sells crypto assets can generally realize gains without U.S. federal income tax, even if the platform or token issuer is based in the United States. The result can differ when income is effectively connected with a U.S. trade or business, or when the transaction produces another type of U.S.-taxable income.
How does the IRS determine whether cryptocurrency income is U.S.-source or foreign-source?
For crypto tax for non-residents, source analysis considers what generated the income and its connection to U.S. activity, rather than relying only on the platform’s location. A passive sale, payment for services, or yield may each require different classification. A tax professional traces the transaction, the taxpayer’s role, and any U.S. business connection before determining the relevant source treatment. Those details help distinguish foreign-source activity from income potentially subject to U.S. federal tax.
Article by
Mahad Mohamed
Mahad Mohamed is an accountant and the CEO of Block3 Finance, with over 26+ years of Canadian and international tax and accounting experience. A crypto accounting specialist since the early days of Bitcoin, he has consulted for over 38 crypto companies and collaborated with legal professionals on regulatory matters. His expertise spans corporate reorganization, cross-border tax structuring (Canada & US), tax disputes, and CRA audits.
Previously, Mahad worked for the Canada Revenue Agency (CRA), Big4 accounting firms, and served as a Rulings Officer for the Federal Tax Authority of the UAE before acquiring Tax Partners in 2014.
Block3 Finance and Tax Partners has 44 full-time accountants and over 9,800+ clients.
Disclaimer
This article provides general information only and is current as of its publication date. It has not been updated and may be out of date. It does not constitute legal advice and should not be relied upon as such. Every tax situation is unique and may differ from the examples discussed in this article. If you have specific questions, you should seek the advice of our accountants for your unique circumstances.
Frequently Asked Questions
Does the source of income matter?
Yes. For U.S. federal tax purposes, a non-U.S. individual is generally subject to tax on passive U.S.-source income or income effectively connected with a U.S. trade or business. The source and character of the income matter more than an exchange’s location alone. For example, a platform based in the United States does not automatically make a nonresident’s passive crypto sale subject to U.S. federal income tax.
How much tax will I pay?
There isn’t one rate for every nonresident crypto transaction. Crypto yield treated as withholdable U.S.-source income may face 30% gross withholding, according to the Internal Revenue Service. Yield treated as effectively connected income may be taxed at rates up to 37% for investing individuals and most trusts. For entities classified as corporations for U.S. tax purposes, the effective rate may be in the range of 45%. Treatment depends on income classification.
How can a crypto tax professional help nonresidents report their cryptocurrency gains to the IRS?
A crypto tax professional can organize transaction data into a filing position by reconciling exchange statements, wallet records, and asset basis. For example, if an exchange history omits a transfer into the account, matching wallet records can help distinguish a transfer from a purchase or taxable disposal. The professional can also separate investment gains from service or yield income, then prepare the relevant calculations and supporting return information.
Is Cryptocurrency reportable in Form 8938 (FATCA)?
For U.S. FATCA reporting, the IRS has not issued set regulations specifically addressing cryptocurrency reporting on Form 8938. This does not establish that every crypto holding is exempt from all reporting. Form 8938 concerns specified foreign financial assets, and the taxpayer’s status and asset details affect the analysis. A professional can assess those facts against the applicable U.S. filing position rather than treating every wallet as identical.
What if you Only Purchase Cryptocurrency and No Other Transactions Made during the year?
For U.S. tax year 2021, a taxpayer whose only virtual currency transactions were purchases using real currency did not have to answer “Yes” to the Form 1040 digital asset question. The example is limited to that tax year and purchase-only activity. A later sale, exchange, payment, reward, or other crypto receipt changes the transaction record and may affect the response and reporting analysis for that year.
How does U.S. crypto tax apply to nonresident aliens?
For crypto tax for non-residents, U.S. treatment generally turns on whether income is passive U.S.-source income or effectively connected with a U.S. trade or business. The label “nonresident alien” alone does not determine the tax treatment of every crypto event. A tax professional considers whether the activity is a passive investment disposal, yield, or business-connected income, then evaluates the relevant U.S. filing obligations for that category.
Are nonresident aliens taxed on cryptocurrency gains from U.S. exchanges?
Not solely because they used a U.S. exchange. A non-U.S. investor who passively sells crypto assets can generally realize gains without U.S. federal income tax, even if the platform or token issuer is based in the United States. The result can differ when income is effectively connected with a U.S. trade or business, or when the transaction produces another type of U.S.-taxable income.
How does the IRS determine whether cryptocurrency income is U.S.-source or foreign-source?
For crypto tax for non-residents, source analysis considers what generated the income and its connection to U.S. activity, rather than relying only on the platform’s location. A passive sale, payment for services, or yield may each require different classification. A tax professional traces the transaction, the taxpayer’s role, and any U.S. business connection before determining the relevant source treatment. Those details help distinguish foreign-source activity from income potentially subject to U.S. federal tax.